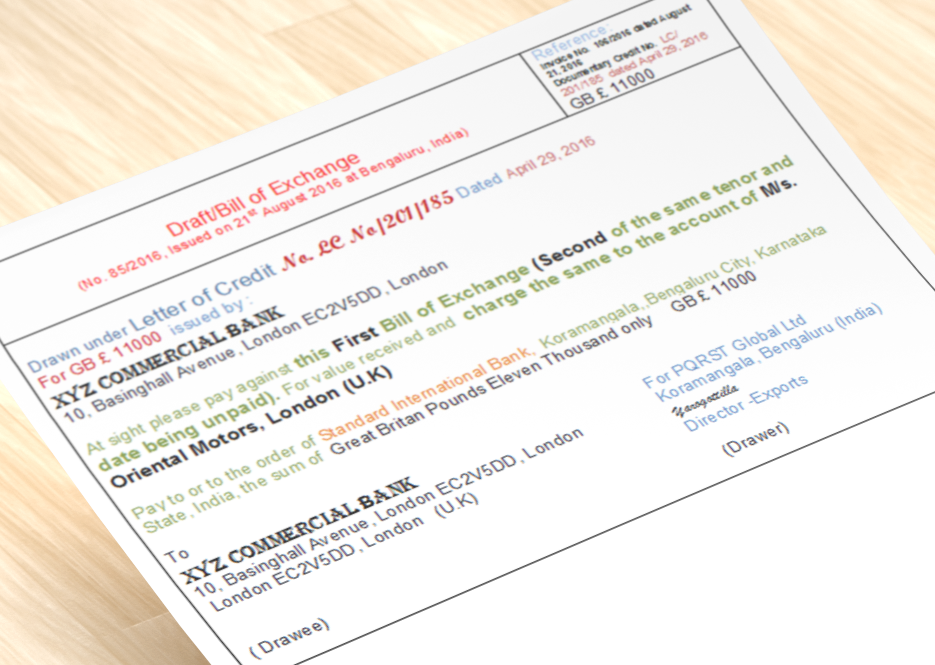
Non-Fund Based Facilities to Non-Constituent Borrowers: RBI Relaxation and Key Conditions
The Reserve Bank of India (RBI), through circular DBOD.Dir.BC.62/13.07.09/2002-03 dated January 24, 2003, had earlier prohibited banks from extending non-fund based facilities to non-constituent borrowers. This restriction was aimed at preventing frauds, fund diversion, and misuse of one-off transaction-based facilities without proper credit assessment. However, over time, this blanket bar created genuine challenges for borrowers…
Read article
How to Claim Overdue Domestic, NRE, and FCNR(B) Deposits Transferred to RBI’s DEA Fund
When Domestic, NRE, or FCNR(B) deposits remain inoperative for 10 consecutive years, banks are required to classify them as unclaimed and transfer the balances to the Depositor Education and Awareness (DEA) Fund maintained by the Reserve Bank of India (RBI). To reclaim these deposits, the customer (or their legal heir) must approach the bank where…
Read article
Understanding Working Capital Appraisal: Key Financial Terms Explained
The working capital requirement of industrial and trading establishments refers to the total funds invested in various current assets such as raw materials (RM), work-in-process (WIP), finished goods (FG), and outstanding receivables. Banks extend working capital facilities to borrowers based on the nature and level of current assets, after deducting the borrower’s margin contribution, within…
Read article
Police Power to Freeze Bank Accounts: Understanding Section 102 CrPC / Section 106 BNSS
Police in India can direct banks to freeze or seize an account if, during investigation, they develop a reasonable suspicion that the account is linked to a crime, but this power is not unlimited and is subject to statutory safeguards and judicial review. The Supreme Court has clarified that a bank account is “property” for…
Read article
UPI–TIPS Interlinkage: Strengthening Cross-Border Instant Payments Between India and the Euro Area
The Reserve Bank of India (RBI)is actively advancing efforts to interlink the **Unified Payments Interface (UPI) with fast payment systems across global jurisdictions to enhance the efficiency of cross-border payments. These initiatives align with the G20 Roadmap for improving cross-border payments, which emphasizes making international transfers cheaper, faster, more transparent, and more accessible. As part…
Cheque Bounce — Is it Necessary to Make Unregistered Firms an Accused? (Updated as of 2025)
A common question arises whether an unregistered partnership firm can be made an accused under Section 141 of the Negotiable Instruments Act, 1881 (NI Act), and whether the firm itself must be arraigned as an accused along with its partners for cheque bounce offences under Section 138. Historically, ambiguity persisted due to Section 69 of…
Read article